Medigap (Medicare Supplement) this fall: the rules and the insurers by state
Published 2026-10-30 · Insurer counts from Medicare.gov's policy search as of 2026-10-12 · Free to republish (CC BY 4.0)
On this page: The paragraph Story angles Guaranteed issue Window calculator Every state Who sells where Download Underwriting approvals Resources Method
Medigap policies are sold by private insurers to people in Original Medicare and pay some of the costs Medicare does not. This fall they matter for one more reason: the Medicare Advantage plans that are not returning (the Medicare Advantage tab has every county) give their members a short window to buy one without health questions.
The numbers in a paragraph
Paste it as is, or take what you need. Please keep the credit: it links readers to the rules and the state table.
Source: MyMedicarePlans.org; Medicare.gov (https://mymedicareplans.org/newsroom/medigap/)
Story angles in the data
- The non-renewals open a Medigap door. 1,150 Medicare Advantage plans are not returning for 2027. People in a plan that is leaving Medicare, or that no longer covers where they live, have a guaranteed issue right: an insurer must sell them certain Medigap policies without asking about their health, if they apply no more than 63 days after the old coverage ends. Many people do not know it, and the window is short.
- Outside that window, health questions. The 6-month Medigap Open Enrollment Period starts the month someone is 65 and has Part B. After it, unless a guaranteed issue right applies, insurers in most states can ask about health and decline or charge more; a few states give more rights (the state insurance department has the rules).
- A one-year trial of Medicare Advantage. Someone who joined Medicare Advantage for the first time in the past 12 months may be able to return to Original Medicare and buy a Medigap policy with the same protection. Medicare.gov's situation finder walks through it.
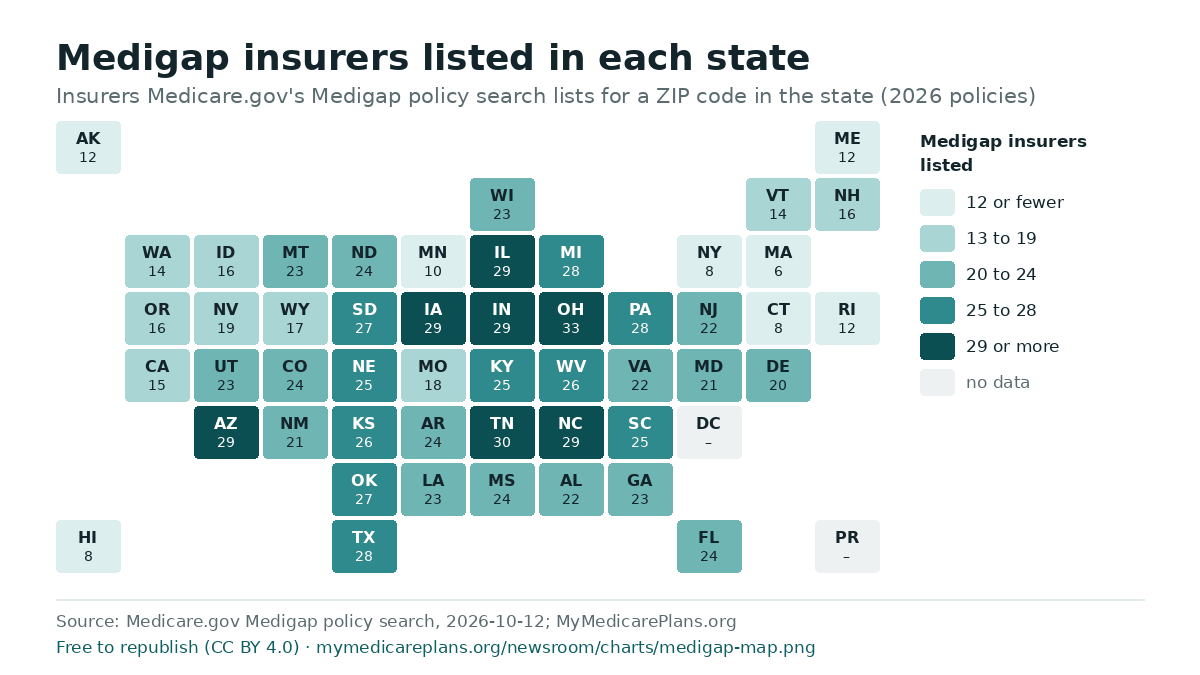
- Where buyers have the fewest insurers. Medicare.gov's policy search listed the fewest Medigap insurers in Massachusetts (6); Connecticut (8); Hawaii (8); New York (8); Minnesota (10); the most in Ohio (33); Tennessee (30); Arizona (29).
- Same letter, same benefits, different price. Plan G from one insurer covers what Plan G from any other covers (outside Massachusetts, Minnesota and Wisconsin, which standardize their own); the premium is what differs, and how the insurer sets it as the buyer ages.
Guaranteed issue rights, in brief
- When a Medicare Advantage plan is leaving Medicare, stops covering the member's area, or the member moves out of it, the member can buy certain Medigap policies sold in the state without medical underwriting.
- Apply no more than 63 days after the old coverage ends, and keep the plan's letter: insurers can ask for proof.
- Someone in their first 12 months of Medicare Advantage may have a trial right to return to Original Medicare and buy a Medigap policy.
- States can add rights. The state insurance department, or a SHIP counselor, confirms what applies.
Medicare.gov walks through each situation: When can I buy Medigap?
Tools and charts for your site
Free to embed or republish with the credit line (CC BY 4.0). The tools carry no ads and no tracking beyond a count of the sites that use them. Everything in one place: Charts & tools.
Your Medigap window: when to apply
Readers enter the day their Medicare Advantage coverage ends and see the dates of their guaranteed issue window, and the insurers in their state.
<iframe src="https://mymedicareplans.org/embed/medigap-window/" title="Your Medigap window: when to apply" width="100%" height="520" style="border:0;max-width:640px" loading="lazy" allowtransparency="true" data-mmp-embed></iframe> <script src="https://mymedicareplans.org/embed/resize.js" async></script> <p style="font:13px/1.4 sans-serif;margin:4px 0 0">When to apply for Medigap: <a href="https://mymedicareplans.org/newsroom/medigap/">MyMedicarePlans.org</a></p>Customize it
Could you be turned down for a Medigap policy?
Readers pick a state: the share of Medicare Advantage enrollees who could be turned down (KFF), the state's windows and switching rules, and the plans ending there.
<iframe src="https://mymedicareplans.org/embed/medigap-underwriting/" title="Could you be turned down for a Medigap policy?" width="100%" height="520" style="border:0;max-width:640px" loading="lazy" allowtransparency="true" data-mmp-embed></iframe> <script src="https://mymedicareplans.org/embed/resize.js" async></script> <p style="font:13px/1.4 sans-serif;margin:4px 0 0">Medigap underwriting by state: <a href="https://mymedicareplans.org/newsroom/medigap/underwriting/">MyMedicarePlans.org</a></p>Customize it
Every state
Insurers listed by Medicare.gov's Medigap policy search for a ZIP code in each state (2026-10-12, 2026 policies). Insurers can differ by ZIP code within a state: the search is the authority for a reader's own ZIP.
| State | Insurers listed | Plans sold (letters) |
|---|---|---|
| Alabama | 22 | A, B, C, D, F, F-HD, G, G-HD, K, L, M, N |
| Alaska | 12 | A, B, C, D, F, F-HD, G, G-HD, K, L, N |
| Arizona | 29 | A, B, C, D, F, F-HD, G, G-HD, K, L, M, N |
| Arkansas | 24 | A, B, C, D, F, F-HD, G, G-HD, K, L, M, N |
| California | 15 | A, B, C, D, F, F-HD, G, G-HD, K, L, N |
| Colorado | 24 | A, B, C, D, F, F-HD, G, G-HD, K, L, N |
| Connecticut | 8 | A, B, C, D, F, F-HD, G, G-HD, K, L, N |
| Delaware | 20 | A, B, C, D, F, F-HD, G, G-HD, K, L, N |
| Florida | 24 | A, B, C, D, F, F-HD, G, G-HD, K, L, M, N |
| Georgia | 23 | A, B, C, D, F, F-HD, G, G-HD, K, L, M, N |
| Hawaii | 8 | A, B, C, D, F, F-HD, G, G-HD, K, L, N |
| Idaho | 16 | A, B, C, D, F, F-HD, G, G-HD, K, L, N |
| Illinois | 29 | A, B, C, D, F, F-HD, G, G-HD, K, L, M, N |
| Indiana | 29 | A, B, C, D, F, F-HD, G, G-HD, K, L, M, N |
| Iowa | 29 | A, B, C, D, F, F-HD, G, G-HD, K, L, M, N |
| Kansas | 26 | A, B, C, D, F, F-HD, G, G-HD, K, L, M, N |
| Kentucky | 25 | A, B, C, D, F, F-HD, G, G-HD, K, L, N |
| Louisiana | 23 | A, B, C, D, F, F-HD, G, G-HD, K, L, M, N |
| Maine | 12 | A, B, C, D, F, F-HD, G, G-HD, K, L, M, N |
| Maryland | 21 | A, B, C, D, F, F-HD, G, G-HD, K, L, M, N |
| Massachusetts | 6 | The state's own standardized plans |
| Michigan | 28 | A, B, C, D, F, F-HD, G, G-HD, K, L, N |
| Minnesota | 10 | The state's own standardized plans |
| Mississippi | 24 | A, B, C, D, F, F-HD, G, G-HD, K, L, M, N |
| Missouri | 18 | A, B, C, D, F, F-HD, G, G-HD, K, L, N |
| Montana | 23 | A, B, C, D, F, F-HD, G, G-HD, K, L, N |
| Nebraska | 25 | A, B, C, D, F, F-HD, G, G-HD, K, L, M, N |
| Nevada | 19 | A, B, C, D, F, F-HD, G, G-HD, K, L, N |
| New Hampshire | 16 | A, B, C, D, F, F-HD, G, G-HD, K, L, M, N |
| New Jersey | 22 | A, B, C, D, F, F-HD, G, G-HD, K, L, M, N |
| New Mexico | 21 | A, B, C, D, F, F-HD, G, G-HD, K, L, N |
| New York | 8 | A, B, C, D, F, F-HD, G, G-HD, K, L, M, N |
| North Carolina | 29 | A, B, C, D, F, F-HD, G, G-HD, K, L, M, N |
| North Dakota | 24 | A, B, C, D, F, F-HD, G, G-HD, K, L, N |
| Ohio | 33 | A, B, C, D, F, F-HD, G, G-HD, K, L, M, N |
| Oklahoma | 27 | A, B, C, D, F, F-HD, G, G-HD, K, L, M, N |
| Oregon | 16 | A, B, C, D, F, F-HD, G, G-HD, K, L, N |
| Pennsylvania | 28 | A, B, C, D, F, F-HD, G, G-HD, K, L, M, N |
| Rhode Island | 12 | A, B, C, D, F, F-HD, G, G-HD, K, L, N |
| South Carolina | 25 | A, B, C, D, F, F-HD, G, G-HD, K, L, M, N |
| South Dakota | 27 | A, B, C, D, F, F-HD, G, G-HD, K, L, N |
| Tennessee | 30 | A, B, C, D, F, F-HD, G, G-HD, K, L, M, N |
| Texas | 28 | A, B, C, D, F, F-HD, G, G-HD, K, L, M, N |
| Utah | 23 | A, B, C, D, F, F-HD, G, G-HD, K, L, M, N |
| Vermont | 14 | A, B, C, D, F, F-HD, G, G-HD, K, L, N |
| Virginia | 22 | A, B, C, D, F, F-HD, G, G-HD, K, L, N |
| Washington | 14 | A, B, C, D, F, F-HD, G, G-HD, K, L, N |
| West Virginia | 26 | A, B, C, D, F, F-HD, G, G-HD, K, L, N |
| Wisconsin | 23 | The state's own standardized plans |
| Wyoming | 17 | A, B, C, D, F, F-HD, G, G-HD, K, L, N |
Who sells Medigap where
152 insurers (by the name Medicare.gov's policy search lists) sell Medigap in at least one state's sample ZIP code; 7 are listed in 40 states or more. The 20 listed in the most states, with the federal plan letters they sell:
| Insurer (as listed) | States | Plan letters |
|---|---|---|
| AARP - UnitedHealthcare Insurance Company | 48 | A B D G G-HD K L N C F |
| Bankers Life (Underwritten by Washington National Insurance Company) | 48 | A B D G G-HD N C F |
| United American Insurance Company | 47 | A B D G G-HD K L N C F F-HD |
| Insurance Company of North America | 45 | A B D G G-HD N C F |
| State Farm Mutual Automobile Insurance Company | 45 | A B D G N C F |
| USAA Life Insurance Company | 45 | A B D G N C F |
| AFLAC | 43 | A B D G N C F |
| GPM Health and Life Insurance Company | 33 | A B D G N C F |
| LifeShield National Insurance Company | 33 | A B D G N C F |
| American Benefit Life Insurance Company | 32 | A B D G N C F |
| Lumos Insurance | 32 | A D G G-HD N C F |
| Guarantee Trust Life Insurance Company | 31 | A B D G N C F F-HD |
| HealthSpring National Health Insurance Company | 26 | A D G G-HD N C F F-HD |
| Wisconsin Physicians Service Insurance Corporation | 26 | A B G K L M N C F |
| WoodmenLife | 25 | A B D G G-HD N C F |
| Humana (Humana Insurance Company) | 21 | A B D G G-HD K L N C F F-HD |
| Humana Achieve (CompBenefits Insurance Company) | 21 | A G G-HD N F |
| Nassau Life Insurance Company | 20 | A B G N F |
| Everence Association Inc. | 18 | A B G L N C F |
| Mutual of Omaha (Mutual of Omaha Insurance Company) | 18 | A B D G G-HD M N C F F-HD |
Plan choices by state. How many listed insurers sell the most-bought letters (G and N, and high-deductible G). Fewest Plan N sellers: Hawaii (6); Connecticut (7); New York (7). Fewest high-deductible G: Hawaii (4); Connecticut (5); New York (5). Massachusetts, Minnesota and Wisconsin standardize their own plans and are left out.
| State | Insurers | Plan G | Plan N | High-deductible G | Plan K | Plan L |
|---|---|---|---|---|---|---|
| Alabama | 22 | 21 | 21 | 12 | 3 | 2 |
| Alaska | 12 | 12 | 11 | 6 | 3 | 3 |
| Arizona | 29 | 29 | 29 | 14 | 4 | 3 |
| Arkansas | 24 | 23 | 23 | 14 | 4 | 2 |
| California | 15 | 15 | 15 | 6 | 3 | 3 |
| Colorado | 24 | 24 | 21 | 11 | 3 | 3 |
| Connecticut | 8 | 8 | 7 | 5 | 2 | 2 |
| Delaware | 20 | 20 | 18 | 10 | 3 | 3 |
| Florida | 24 | 24 | 23 | 11 | 3 | 4 |
| Georgia | 23 | 21 | 22 | 12 | 3 | 2 |
| Hawaii | 8 | 8 | 6 | 4 | 2 | 2 |
| Idaho | 16 | 16 | 16 | 7 | 4 | 2 |
| Illinois | 29 | 28 | 29 | 15 | 3 | 3 |
| Indiana | 29 | 29 | 28 | 13 | 3 | 3 |
| Iowa | 29 | 29 | 28 | 14 | 4 | 4 |
| Kansas | 26 | 26 | 25 | 12 | 4 | 4 |
| Kentucky | 25 | 25 | 25 | 11 | 2 | 2 |
| Louisiana | 23 | 23 | 23 | 14 | 2 | 2 |
| Maine | 12 | 12 | 11 | 6 | 3 | 3 |
| Maryland | 21 | 21 | 20 | 9 | 2 | 4 |
| Michigan | 28 | 28 | 28 | 13 | 2 | 3 |
| Mississippi | 24 | 23 | 23 | 13 | 3 | 2 |
| Missouri | 18 | 18 | 17 | 9 | 3 | 3 |
| Montana | 23 | 23 | 21 | 10 | 5 | 3 |
| Nebraska | 25 | 24 | 24 | 10 | 3 | 5 |
| Nevada | 19 | 19 | 18 | 9 | 2 | 2 |
| New Hampshire | 16 | 16 | 16 | 7 | 3 | 3 |
| New Jersey | 22 | 21 | 22 | 13 | 4 | 2 |
| New Mexico | 21 | 19 | 20 | 10 | 3 | 2 |
| New York | 8 | 8 | 7 | 5 | 4 | 4 |
| North Carolina | 29 | 29 | 28 | 16 | 4 | 2 |
| North Dakota | 24 | 24 | 24 | 8 | 3 | 3 |
| Ohio | 33 | 33 | 32 | 18 | 4 | 3 |
| Oklahoma | 27 | 27 | 24 | 12 | 2 | 3 |
| Oregon | 16 | 16 | 16 | 6 | 4 | 4 |
| Pennsylvania | 28 | 27 | 27 | 14 | 1 | 2 |
| Rhode Island | 12 | 12 | 11 | 6 | 3 | 3 |
| South Carolina | 25 | 25 | 24 | 14 | 4 | 4 |
| South Dakota | 27 | 26 | 27 | 11 | 5 | 5 |
| Tennessee | 30 | 29 | 28 | 14 | 2 | 2 |
| Texas | 28 | 27 | 25 | 14 | 3 | 2 |
| Utah | 23 | 23 | 23 | 9 | 4 | 3 |
| Vermont | 14 | 13 | 14 | 5 | 1 | 1 |
| Virginia | 22 | 22 | 21 | 10 | 2 | 2 |
| Washington | 14 | 14 | 13 | 7 | 2 | 1 |
| West Virginia | 26 | 26 | 26 | 11 | 3 | 3 |
| Wyoming | 17 | 17 | 17 | 9 | 5 | 3 |
Insurers by state count (CSV)Plan letters by state (CSV)
Free to republish
The charts and data on this page are free to use under Creative Commons Attribution 4.0: credit MyMedicarePlans.org with a link to this page. The CSV has one row a state: the insurers listed and the plan letters sold.
Underwriting: who could be turned down
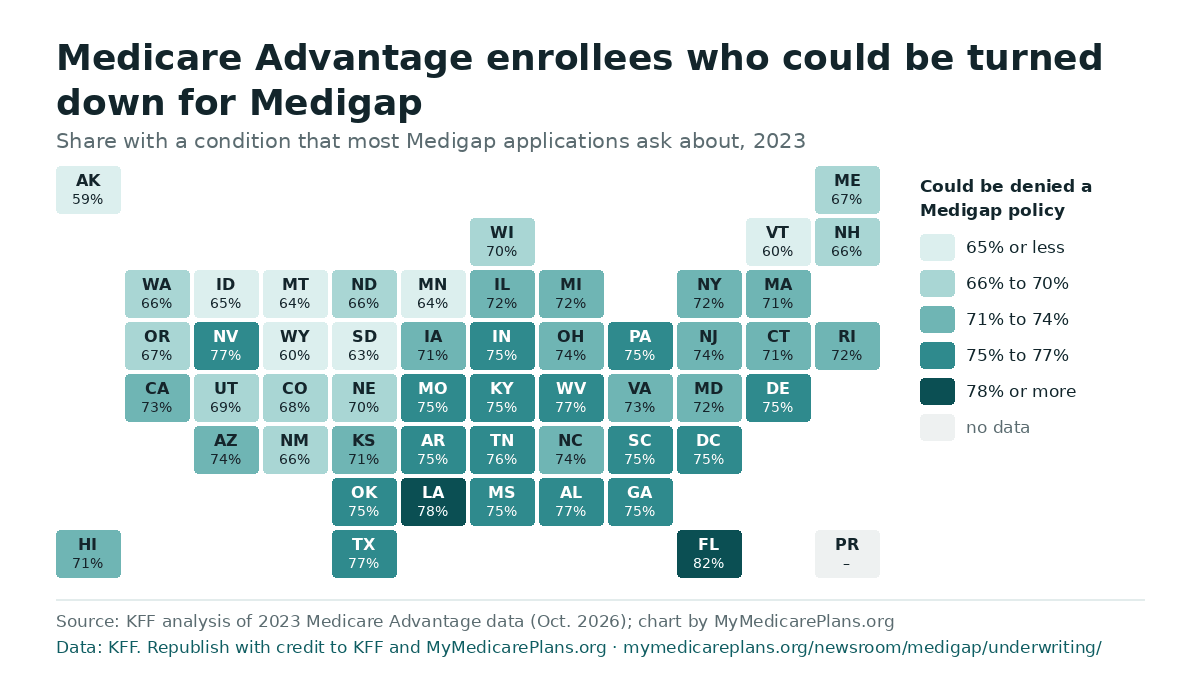
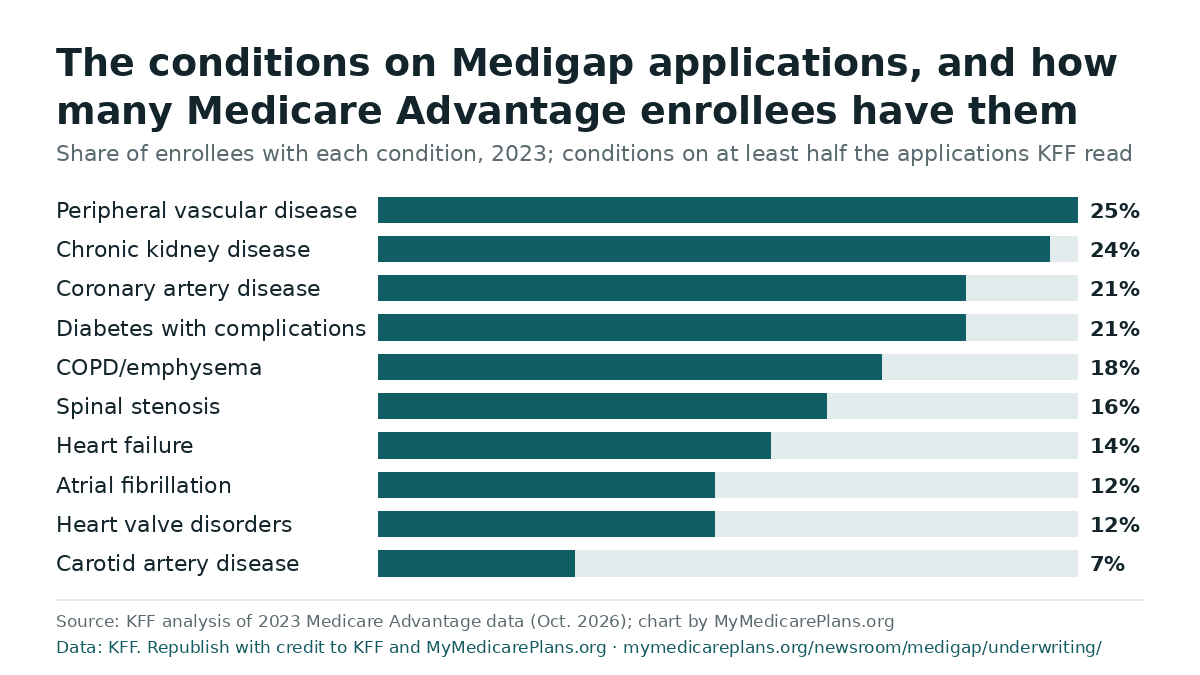
74% of Medicare Advantage enrollees, about 20.9 million people, had a condition that could get them turned down for a Medigap policy outside a guaranteed issue window, KFF found; the share runs from 59% in Alaska to 82% in Florida. No insurer publishes its approval or decline rates. Every state, the conditions, the state windows and a lookup to embed.
Medigap insurers by state: every company Medicare.gov lists in 50 states, by name, with the plan letters each sells. Free CSV downloads, CC BY 4.0.
Official resources
Medigap
- Medigap on Medicare.gov: what Medigap covers and how it works with Original Medicare
- Medigap policy search: the policies and insurers sold in a ZIP code
- When can I buy Medigap?: Medicare.gov's walk-through of the open enrollment period and guaranteed issue rights
- Choosing a Medigap Policy (guide): the federal guide, with every plan letter's benefits
- State insurance departments: each state's own Medigap rules and rate filings (NAIC directory)
Medicare
- Medicare.gov: the official site; 1-800-MEDICARE (1-800-633-4227) answers around the clock
- Medicare Plan Finder: every Medicare Advantage and Part D plan by ZIP code, with drug costs
- Medicare & You: the yearly handbook mailed to every household with Medicare
- CMS newsroom: press releases, fact sheets and the press office
- CMS data: enrollment, spending and plan data sets
- SHIP (State Health Insurance Assistance Programs): free, unbiased local counseling in every state
- Social Security: Medicare: signing up for Parts A and B, and Part B premiums
- Eldercare Locator: local aging services, from the Administration for Community Living
- Senior Medicare Patrol: Medicare fraud and scams: reporting and education
- Medicare Rights Center: a nonprofit helpline and plain-language guides
- KFF on Medicare: independent research and polling on Medicare
For your readers
Medicare Supplement (Medigap) by state, the site's pages for people comparing policies.
Where the facts come from
The rules: Medicare.gov's Medigap pages and the federal guide Choosing a Medigap Policy. The insurer counts: Medicare.gov's Medigap policy search, one ZIP code a state. The Medicare Advantage count: the newsroom's comparison of the CMS Landscape files.
Embed the tables on this page
Every table here can go on your site: searchable, sortable, filterable, with the CSV a click away. Paste the code where the table should appear. It sizes itself to fit; add ?state=ohio to start on a state, or ?bg=transparent to sit on your page's own background. Fonts, colors and the rest: the Embed Studio.
Medigap insurers by state
How many insurers Medicare.gov lists in each state, and the plan letters sold.
<iframe src="https://mymedicareplans.org/embed/table/medigap-states/" title="Medigap insurers by state" width="100%" height="640" style="border:0" loading="lazy" allowtransparency="true" data-mmp-embed></iframe> <script src="https://mymedicareplans.org/embed/resize.js" async></script> <p style="font:13px/1.4 sans-serif;margin:4px 0 0">Medigap insurers by state: <a href="https://mymedicareplans.org/newsroom/medigap/">MyMedicarePlans.org</a></p>Customize it Preview
Medigap plan letters sold, by state
How many insurers sell each Medigap plan letter in each state.
<iframe src="https://mymedicareplans.org/embed/table/medigap-plan-letters/" title="Medigap plan letters sold, by state" width="100%" height="640" style="border:0" loading="lazy" allowtransparency="true" data-mmp-embed></iframe> <script src="https://mymedicareplans.org/embed/resize.js" async></script> <p style="font:13px/1.4 sans-serif;margin:4px 0 0">Medigap plan letters sold, by state: <a href="https://mymedicareplans.org/newsroom/medigap/">MyMedicarePlans.org</a></p>Customize it Preview
Medigap insurers and where they sell
Every Medigap insurer: the states it is listed in and the plan letters.
<iframe src="https://mymedicareplans.org/embed/table/medigap-insurer-footprint/" title="Medigap insurers and where they sell" width="100%" height="640" style="border:0" loading="lazy" allowtransparency="true" data-mmp-embed></iframe> <script src="https://mymedicareplans.org/embed/resize.js" async></script> <p style="font:13px/1.4 sans-serif;margin:4px 0 0">Medigap insurers and where they sell: <a href="https://mymedicareplans.org/newsroom/medigap/">MyMedicarePlans.org</a></p>Customize it Preview
Questions about the data
Write to [email protected]: a custom cut of the data (a county list, a region, a chart in your outlet's size) is usually a same-day reply.
For a quote or an interview, write to the same address and the desk that covers it answers: the Data Desk for the plan counts and the county data, the Costs & Policy Desk for Part D, premiums, IRMAA and Extra Help, the Editorial Desk for how Medicare works, Medigap and enrollment. Every answer comes from the CMS files and Medicare's own rules.
MyMedicarePlans.org is a Medicare guide: plain-language answers and plan data for people choosing coverage. The counts here come only from the CMS files, and the method is above. Not connected with or endorsed by the U.S. government or the federal Medicare program.